Relative Strength Index (RSI)
Summary
Wilder's Relative Strength Index, a momentum oscillator bounded 0-100 from the ratio of average gains to average losses over the period. Used to gauge overbought/oversold conditions. >70 overbought, <30 oversold.
Chart
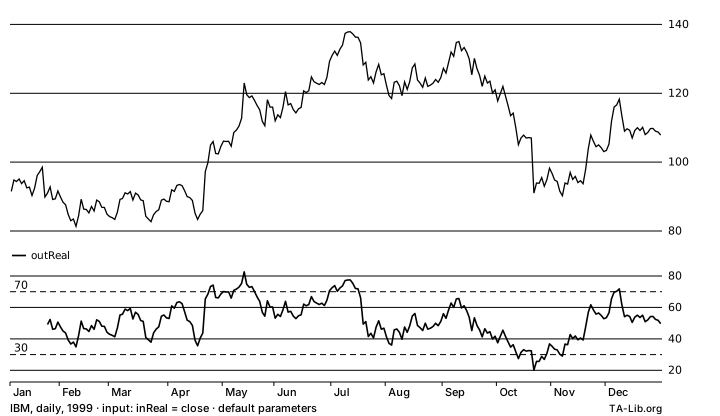
Chart metadata i
Outputs
outReal:line·zero·positive·levels: 30, 70
Formula
where is the input series and the period.
Notes
- While the input has not changed since the first bar the call reads, there is neither a gain nor a loss and RSI is 0/0: the output is the neutral 50. Up to 0.8.1 it was 0, which read as oversold. Input that has only risen gives 100 and input that has only fallen gives 0.
- After a move, an unchanged input holds the last value until the two averages decay to rounding residue: about a thousand unchanged bars at period 2, about ten thousand at period 14. The output then drifts and settles on 50. Input that had only risen or only fallen stays at 100 or 0, except at period 2.
Inputs
inReal— Price series (typically close)
Outputs
outReal— RSI value
Parameters
| Parameter | Type | Default | Accepted values | Description |
|---|---|---|---|---|
optInTimePeriod | integer | 14 | 2–100000 | Lookback for the gain/loss averaging |
Properties
Numerical Stability: Initial Unstable Period
| ☐ Overlap Input |
| ✅ Independent Y-Axis i |
| ☐ Candlestick |
| ☐ Display Shift |
| ☐ Can Output NaN or ±Inf |
| ☐ Identity at Period 1 |
| ☐ Uses Transcendental |
| ☐ Input Must Be Positive |
Example
C
#include <stdio.h>
#include <ta_libc.h>

int n = 252;
double series[252]; /* your data, oldest first */
double out[252];
int outBegIdx, outNBElement;

TA_Initialize();
TA_RSI( 0, n - 1, series, 14, &outBegIdx, &outNBElement, out );
printf( "%d values from bar %d; last out = %f\n", outNBElement, outBegIdx, out[outNBElement - 1] );
Rust
use ta_lib::Core;

let series = vec![0.0; 252]; // your data, oldest first
let mut out = vec![0.0; 252];

let core = Core::new();
let range = core.rsi(0, series.len() - 1, &series, 14, &mut out)?;
println!("{} values from bar {}; last out = {}", range.count, range.beg_idx, out[range.count - 1]);
Java
import io.github.talib.Core;
import io.github.talib.OutRange;

double[] series = new double[252]; // your data, oldest first
double[] out = new double[252];

Core core = Core.DEFAULT;
OutRange r = core.rsi(0, series.length - 1, series, 14, out);
System.out.println(r.count() + " values from bar " + r.begIdx() + "; last out = " + out[r.count() - 1]);
C#
using System;
using TALib;

var series = new double[252]; // your data, oldest first
var outReal = new double[252];

var core = Core.Default;
OutRange r = core.Rsi(0, series.Length - 1, series, 14, outReal);
Console.WriteLine($"{r.Count} values from bar {r.BegIdx}; last outReal = {outReal[r.Count - 1]}");
TypeScript
import { rsi } from 'ta-lib';

const series = new Float64Array(252); // your data, oldest first

const { begIdx, values } = rsi(series, { timePeriod: 14 });
console.log(values.length + ' values from bar ' + begIdx + '; last values = ' + values[values.length - 1]);
Implementation
Added in 0.4.0.
TA-Lib Definition: rsi.c · rsi.yaml
| Native | File |
|---|---|
| C | ta_RSI.c |
| Rust | rsi.rs |
| Java | Core_RSI.java |
| C# | Core_RSI.cs |
| TypeScript | rsi.ts |
Python: talib.RSI, see ta-lib-python.
TA-Lib is also available for R and more using a wrapper.
Aliases
relative strength index
See Also
References
- J. Welles Wilder, New Concepts in Technical Trading Systems, Trend Research (ISBN 0894590278)