Chande Momentum Oscillator (CMO)
Summary
Chande Momentum Oscillator: bounded momentum measure from Wilder-smoothed average up-moves and down-moves. Identical to RSI except the numerator uses (gain-loss) instead of gain. Bounded in [-100,+100]; positive = net upward momentum, negative = net downward.
Chart
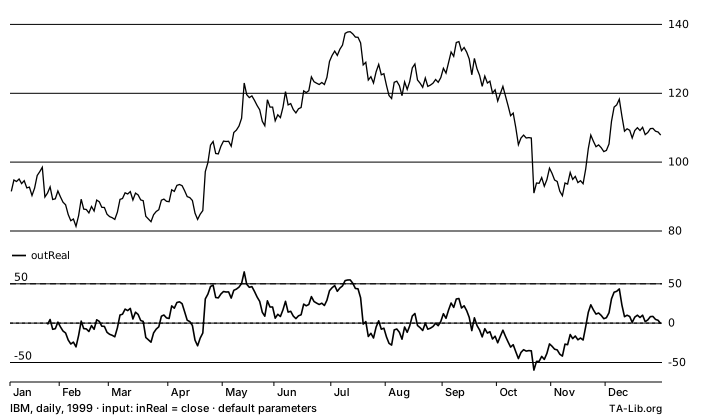
Chart metadata i
Outputs
outReal:line·zero·positive·negative·levels: -50, 50
Formula
d = P[t]-P[t-1]; over the initial period accumulate gain = sum of positive d, loss = sum of -d for negative d. Wilder-smooth each: prevGain = (prevGain*(period-1) + gain_today)/period (same for loss). CMO = 100 * (prevGain-prevLoss)/(prevGain+prevLoss); 0 when prevGain+prevLoss == 0.
Notes
- Gains and losses are smoothed with Wilder's method (as in RSI) rather than the simple period sums of Chande's original definition.
Inputs
inReal— Source price/value series
Outputs
outReal— CMO oscillator value
Parameters
| Parameter | Type | Default | Accepted values | Description |
|---|---|---|---|---|
optInTimePeriod | integer | 14 | 2–100000 | Bars over which gains/losses are smoothed |
Properties
Numerical Stability: Initial Unstable Period
| ☐ Overlap Input |
| ✅ Independent Y-Axis i |
| ☐ Candlestick |
| ☐ Display Shift |
| ☐ Can Output NaN or ±Inf |
| ☐ Identity at Period 1 |
| ☐ Uses Transcendental |
| ☐ Input Must Be Positive |
Example
#include <stdio.h>
#include <ta_libc.h>

int n = 252;
double series[252]; /* your data, oldest first */
double out[252];
int outBegIdx, outNBElement;

TA_Initialize();
TA_CMO( 0, n - 1, series, 14, &outBegIdx, &outNBElement, out );
printf( "%d values from bar %d; last out = %f\n", outNBElement, outBegIdx, out[outNBElement - 1] );use ta_lib::Core;
let series = vec![0.0; 252]; // your data, oldest first
let mut out = vec![0.0; 252];
let core = Core::new();
let range = core.cmo(0, series.len() - 1, &series, 14, &mut out)?;
println!("{} values from bar {}; last out = {}", range.count, range.beg_idx, out[range.count - 1]);import io.github.talib.Core;
import io.github.talib.OutRange;
double[] series = new double[252]; // your data, oldest first
double[] out = new double[252];
Core core = Core.DEFAULT;
OutRange r = core.cmo(0, series.length - 1, series, 14, out);
System.out.println(r.count() + " values from bar " + r.begIdx() + "; last out = " + out[r.count() - 1]);using System;
using TALib;
var series = new double[252]; // your data, oldest first
var outReal = new double[252];
var core = Core.Default;
OutRange r = core.Cmo(0, series.Length - 1, series, 14, outReal);
Console.WriteLine($"{r.Count} values from bar {r.BegIdx}; last outReal = {outReal[r.Count - 1]}");import { cmo } from 'ta-lib';
const series = new Float64Array(252); // your data, oldest first
const { begIdx, values } = cmo(series, { timePeriod: 14 });
console.log(values.length + ' values from bar ' + begIdx + '; last values = ' + values[values.length - 1]);Implementation
Added in 0.4.0.
TA-Lib Definition: cmo.c · cmo.yaml
| Native | File |
|---|---|
| C | ta_CMO.c |
| Rust | cmo.rs |
| Java | Core_CMO.java |
| C# | Core_CMO.cs |
| TypeScript | cmo.ts |
Python: talib.CMO, see ta-lib-python.
TA-Lib is also available for R and more using a wrapper.
Aliases
Chande Momentum Oscillator
See Also
References
- Tushar S. Chande, The New Technical Trader, John Wiley & Sons (ISBN 0471597805)