Klinger Volume Oscillator (KVO)
Summary
Klinger Volume Oscillator: each bar's volume is signed by the direction of its high-low-close sum and weighted by where the bar's own range sits inside the cumulative range of the current trend run, then the resulting volume force is smoothed twice and differenced. Klinger's reading is that volume alone says how much trading happened but not what it accomplished, so he scales it by the share of the trend's accumulated range that this bar actually covered. The oscillator crosses zero as the balance of that force changes hands, and crosses its own trigger line earlier.
Chart
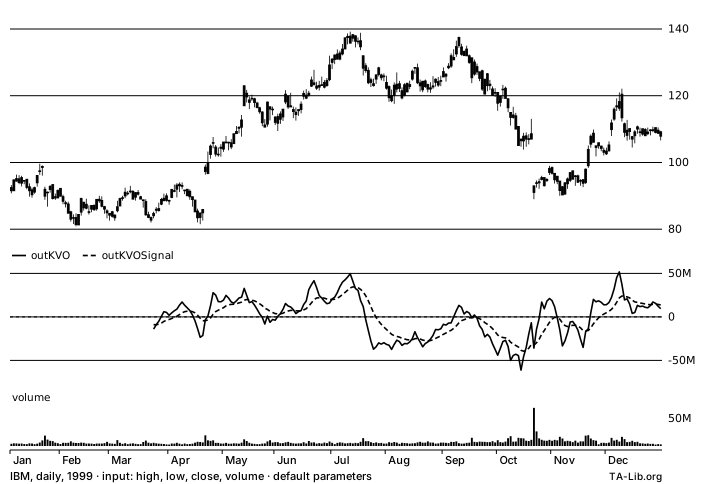
Chart metadata i
Outputs
outKVO:line·zero·positive·negativeoutKVOSignal:dash_line·zero·positive·negative
Formula
hlc = high + low + close; dm = high - low
trend = +1 if hlc rose, -1 if hlc fell, unchanged if hlc repeated
cm = previous dm + current dm on a trend change, otherwise previous cm + current dm
vf = volume * |2 * (dm / cm) - 1| * 100 * trend
KVO = EMA(vf, fastPeriod) - EMA(vf, slowPeriod)
Signal = EMA(KVO, signalPeriod)
Notes
- The trend is held when the high-low-close sum repeats, which is the article's own tenet: the existing trend is maintained on equality. A reading that breaks the tie in either direction changes every later bar, because the cumulative range is reset by a trend change.
- The cumulative range is reset by every trend change, so two calls starting at different bars carry different range state only until the first trend change after both; what remains between them is the seed error of the three averages, which fades at the rate of the longest period. KVO converges, but as a small difference of two large averages it needs more bars than one of them would.
- All three exponential averages are seeded from the volume force of the same anchor bar rather than from a simple average of their own first inputs, so one warm-up covers all three. KVO is exactly zero on that seed bar, which falls inside the warm-up and is never output.
TA_SetUnstablePeriod(TA_FUNC_UNST_EMA, ...)discards more of that warm-up. - The weight is the 1997 form,
|2*(dm/cm) - 1|, which is what the December 1997 Traders' Tips print. Some later implementations use|2*(dm/cm - 1)|, which is a different series. - A cumulative range of exactly zero leaves the volume force at zero rather than dividing.
Inputs
inHigh— High price seriesinLow— Low price seriesinClose— Close price seriesinVolume— Volume series
Outputs
outKVO— Klinger Volume OscillatoroutKVOSignal— Trigger line, an exponential average of the oscillator
Parameters
| Parameter | Type | Default | Accepted values | Description |
|---|---|---|---|---|
optInFastPeriod | integer | 34 | 2–100000 | Period of the faster smoothing of the volume force |
optInSlowPeriod | integer | 55 | 2–100000 | Period of the slower smoothing of the volume force |
optInSignalPeriod | integer | 13 | 2–100000 | Smoothing period of the trigger line |
Properties
Numerical Stability: Initial Unstable Period — Inherited from EMA, which KVO computes internally; tunable via EMA's unstable period.
| ☐ Overlap Input |
| ✅ Independent Y-Axis i |
| ☐ Candlestick |
| ☐ Display Shift |
| ☐ Can Output NaN or ±Inf |
| ☐ Identity at Period 1 |
| ☐ Uses Transcendental |
| ☐ Input Must Be Positive |
Example
#include <stdio.h>
#include <ta_libc.h>

int n = 252;
double high[252]; /* your data, oldest first */
double low[252]; /* your data, oldest first */
double close[252]; /* your data, oldest first */
double volume[252]; /* your data, oldest first */
double kvo[252], kvoSignal[252];
int outBegIdx, outNBElement;

TA_Initialize();
TA_KVO( 0, n - 1, high, low, close, volume, 34, 55, 13, &outBegIdx, &outNBElement, kvo, kvoSignal );
printf( "%d values from bar %d; last kvo = %f\n", outNBElement, outBegIdx, kvo[outNBElement - 1] );use ta_lib::Core;
let high = vec![0.0; 252]; // your data, oldest first
let low = vec![0.0; 252]; // your data, oldest first
let close = vec![0.0; 252]; // your data, oldest first
let volume = vec![0.0; 252]; // your data, oldest first
let mut kvo = vec![0.0; 252];
let mut kvo_signal = vec![0.0; 252];
let core = Core::new();
let range = core.kvo(0, high.len() - 1, &high, &low, &close, &volume, 34, 55, 13,
&mut kvo, &mut kvo_signal)?;
println!("{} values from bar {}; last kvo = {}", range.count, range.beg_idx, kvo[range.count - 1]);import io.github.talib.Core;
import io.github.talib.OutRange;
double[] high = new double[252]; // your data, oldest first
double[] low = new double[252]; // your data, oldest first
double[] close = new double[252]; // your data, oldest first
double[] volume = new double[252]; // your data, oldest first
double[] kvo = new double[252];
double[] kvoSignal = new double[252];
Core core = Core.DEFAULT;
OutRange r = core.kvo(0, high.length - 1, high, low, close, volume, 34, 55, 13, kvo, kvoSignal);
System.out.println(r.count() + " values from bar " + r.begIdx() + "; last kvo = " + kvo[r.count() - 1]);using System;
using TALib;
var high = new double[252]; // your data, oldest first
var low = new double[252]; // your data, oldest first
var close = new double[252]; // your data, oldest first
var volume = new double[252]; // your data, oldest first
var kvo = new double[252];
var kvoSignal = new double[252];
var core = Core.Default;
OutRange r = core.Kvo(0, high.Length - 1, high, low, close, volume, 34, 55, 13, kvo, kvoSignal);
Console.WriteLine($"{r.Count} values from bar {r.BegIdx}; last kvo = {kvo[r.Count - 1]}");import { kvo } from 'ta-lib';
const high = new Float64Array(252); // your data, oldest first
const low = new Float64Array(252); // your data, oldest first
const close = new Float64Array(252); // your data, oldest first
const volume = new Float64Array(252); // your data, oldest first
const { begIdx, outKvo, outKvoSignal } = kvo({ high, low, close, volume }, {
fastPeriod: 34,
slowPeriod: 55,
signalPeriod: 13,
});
console.log(outKvo.length + ' values from bar ' + begIdx + '; last outKvo = ' + outKvo[outKvo.length - 1]);Implementation
Added in 0.8.3 (ta-lib-python 0.8.3).
TA-Lib Definition: kvo.c · kvo.yaml
| Native | File |
|---|---|
| C | ta_KVO.c |
| Rust | kvo.rs |
| Java | Core_KVO.java |
| C# | Core_KVO.cs |
| TypeScript | kvo.ts |
Python: talib.KVO (ta-lib-python 0.8.3 or later), see ta-lib-python.
TA-Lib is also available for R and more using a wrapper.
Aliases
klinger, klinger volume oscillator, klinger oscillator
See Also
References
- Stephen J. Klinger, "Identifying Trends With Volume Analysis", Technical Analysis of Stocks & Commodities, v15:12 (December 1997)