Hilbert Transform - Dominant Cycle Period (HT_DCPERIOD)
Summary
Hilbert Transform estimate of the dominant cycle period (in bars) of the price series. Outputs the smoothed instantaneous cycle period. Output is the estimated dominant cycle length in bars (clamped to 6-50).
Chart
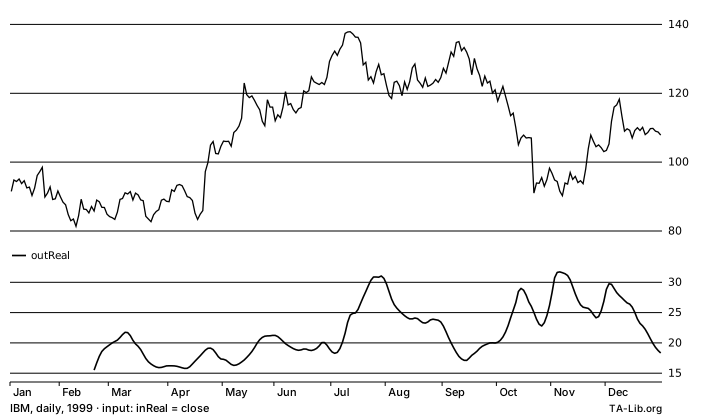
Chart metadata i
Outputs
outReal:line·positive
Inputs
inReal— Source price/value series
Outputs
outReal— Smoothed dominant cycle period in bars
Properties
Numerical Stability: Initial Unstable Period
| ☐ Overlap Input |
| ✅ Independent Y-Axis i |
| ☐ Candlestick |
| ☐ Display Shift |
| ☐ Can Output NaN or ±Inf |
| ☐ Identity at Period 1 |
| ✅ Uses Transcendental i |
| ☐ Input Must Be Positive |
Example
C
#include <stdio.h>
#include <ta_libc.h>

int n = 252;
double series[252]; /* your data, oldest first */
double out[252];
int outBegIdx, outNBElement;

TA_Initialize();
TA_HT_DCPERIOD( 0, n - 1, series, &outBegIdx, &outNBElement, out );
printf( "%d values from bar %d; last out = %f\n", outNBElement, outBegIdx, out[outNBElement - 1] );
Rust
use ta_lib::Core;

let series = vec![0.0; 252]; // your data, oldest first
let mut out = vec![0.0; 252];

let core = Core::new();
let range = core.ht_dcperiod(0, series.len() - 1, &series, &mut out)?;
println!("{} values from bar {}; last out = {}", range.count, range.beg_idx, out[range.count - 1]);
Java
import io.github.talib.Core;
import io.github.talib.OutRange;

double[] series = new double[252]; // your data, oldest first
double[] out = new double[252];

Core core = Core.DEFAULT;
OutRange r = core.htDcperiod(0, series.length - 1, series, out);
System.out.println(r.count() + " values from bar " + r.begIdx() + "; last out = " + out[r.count() - 1]);
C#
using System;
using TALib;

var series = new double[252]; // your data, oldest first
var outReal = new double[252];

var core = Core.Default;
OutRange r = core.HtDcperiod(0, series.Length - 1, series, outReal);
Console.WriteLine($"{r.Count} values from bar {r.BegIdx}; last outReal = {outReal[r.Count - 1]}");
TypeScript
import { htDcperiod } from 'ta-lib';

const series = new Float64Array(252); // your data, oldest first

const { begIdx, values } = htDcperiod(series);
console.log(values.length + ' values from bar ' + begIdx + '; last values = ' + values[values.length - 1]);
Implementation
Added in 0.4.0.
TA-Lib Definition: ht_dcperiod.c · ht_dcperiod.yaml
| Native | File |
|---|---|
| C | ta_HT_DCPERIOD.c |
| Rust | ht_dcperiod.rs |
| Java | Core_HT_DCPERIOD.java |
| C# | Core_HT_DCPERIOD.cs |
| TypeScript | htDcperiod.ts |
Python: talib.HT_DCPERIOD, see ta-lib-python.
TA-Lib is also available for R and more using a wrapper.
Aliases
Hilbert Transform Dominant Cycle Period, Dominant Cycle Period
See Also
HT_DCPHASE · HT_PHASOR · HT_SINE · HT_TRENDMODE · MAMA · WMA
References
- John F. Ehlers, Rocket Science for Traders: Digital Signal Processing Applications, John Wiley & Sons (ISBN 0471405671)