Market Facilitation Index (MARKETFI)
Summary
Bill Williams' Market Facilitation Index (Trading Chaos, 1995): the price range a bar travelled per unit of volume traded — how much movement the market "facilitated" per tick. A rising index on rising volume is read as a move the market is absorbing; a rising index on falling volume as one it is not.
Retail material commonly abbreviates this "MFI" or "BW MFI". TA-Lib already ships TA_MFI for the Money Flow Index, so this carries the MARKETFI name used by Tulip and pandas-ta-classic.
Charting packages often overlay a four-state colour code (green / fade / fake / squat) derived from the signs of the bar-to-bar change in this index and in volume. That is an interpretive layer on top of the series, not part of it; outReal is the scalar only.
Chart
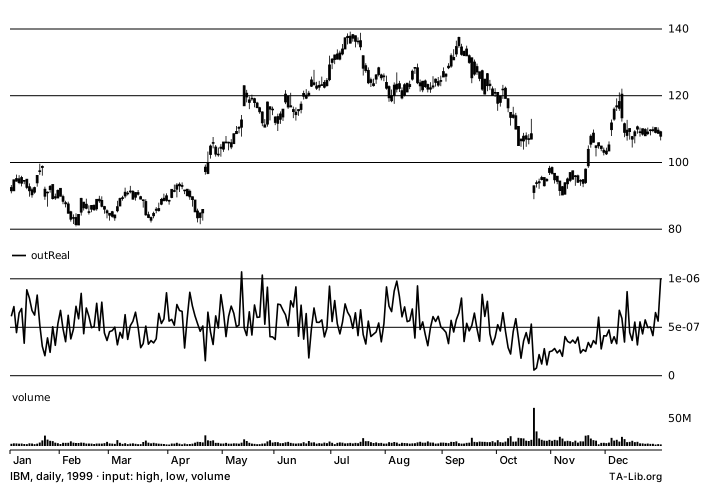
Chart metadata i
Outputs
outReal:line·zero·positive
Formula
MARKETFI_t = (high_t - low_t) / volume_t
A bar with zero volume reports 0 rather than dividing: it facilitated no movement, and a successful call never emits NaN or ±Inf.
Inputs
inHigh— High price of each barinLow— Low price of each barinVolume— Volume of each bar
Outputs
outReal— Range travelled per unit of volume, per bar
Properties
Numerical Stability: Start-Independent
| ☐ Overlap Input |
| ✅ Independent Y-Axis i |
| ☐ Candlestick |
| ☐ Display Shift |
| ☐ Can Output NaN or ±Inf |
| ☐ Identity at Period 1 |
| ☐ Uses Transcendental |
| ☐ Input Must Be Positive |
Example
#include <stdio.h>
#include <ta_libc.h>

int n = 252;
double high[252]; /* your data, oldest first */
double low[252]; /* your data, oldest first */
double volume[252]; /* your data, oldest first */
double out[252];
int outBegIdx, outNBElement;

TA_Initialize();
TA_MARKETFI( 0, n - 1, high, low, volume, &outBegIdx, &outNBElement, out );
printf( "%d values from bar %d: [%.4f, ..., %.4f]\n", outNBElement, outBegIdx, out[0], out[outNBElement - 1] );use ta_lib::Core;
let high = vec![0.0; 252]; // your data, oldest first
let low = vec![0.0; 252]; // your data, oldest first
let volume = vec![0.0; 252]; // your data, oldest first
let mut out = vec![0.0; 252];
let core = Core::new();
let range = core.marketfi(0, high.len() - 1, &high, &low, &volume, &mut out)?;
println!("{} values from bar {}: [{:.4}, ..., {:.4}]", range.count, range.beg_idx, out[0], out[range.count - 1]);import io.github.talib.Core;
import io.github.talib.OutRange;
import java.util.Locale;
double[] high = new double[252]; // your data, oldest first
double[] low = new double[252]; // your data, oldest first
double[] volume = new double[252]; // your data, oldest first
double[] out = new double[252];
Core core = Core.DEFAULT;
OutRange r = core.marketfi(0, high.length - 1, high, low, volume, out);
System.out.printf(Locale.ROOT, "%d values from bar %d: [%.4f, ..., %.4f]%n", r.count(), r.begIdx(), out[0], out[r.count() - 1]);using System;
using TALib;
var high = new double[252]; // your data, oldest first
var low = new double[252]; // your data, oldest first
var volume = new double[252]; // your data, oldest first
var outReal = new double[252];
var core = Core.Default;
OutRange r = core.Marketfi(0, high.Length - 1, high, low, volume, outReal);
Console.WriteLine(FormattableString.Invariant($"{r.Count} values from bar {r.BegIdx}: [{outReal[0]:F4}, ..., {outReal[r.Count - 1]:F4}]"));import { marketfi } from 'ta-lib';
const high = new Float64Array(252); // your data, oldest first
const low = new Float64Array(252); // your data, oldest first
const volume = new Float64Array(252); // your data, oldest first
const { begIdx, values } = marketfi({ high, low, volume });
console.log(values.length + ' values from bar ' + begIdx + ': [' + values[0].toFixed(4) + ', ..., ' + values[values.length - 1].toFixed(4) + ']');import (
"fmt"
"log"
talib "ta-lib.github.io/go"
)
high := make([]float64, 252) // your data, oldest first
low := make([]float64, 252) // your data, oldest first
volume := make([]float64, 252) // your data, oldest first
out := make([]float64, 252)
core := talib.NewCore()
r, err := core.MARKETFI(0, len(high)-1, high, low, volume, out)
if err != nil {
log.Fatal(err)
}
fmt.Printf("%d values from bar %d: [%.4f, ..., %.4f]\n", r.NBElement, r.BegIdx, out[0], out[r.NBElement-1])Implementation
Added in 0.8.1 (ta-lib-python 0.8.1).
TA-Lib Definition: marketfi.c · marketfi.yaml
| Native | File |
|---|---|
| C | ta_MARKETFI.c |
| Rust | marketfi.rs |
| Java | Core_MARKETFI.java |
| C# | Core_MARKETFI.cs |
| TypeScript | marketfi.ts |
| Go | marketfi.go |
Python: talib.MARKETFI (ta-lib-python 0.8.1 or later), see ta-lib-python.
TA-Lib is also available for R and more using a wrapper.
See Also
References
- Bill Williams, Trading Chaos, 1995, introduces the Market Facilitation Index as the price range a bar travelled per unit of volume.
- Tulip Indicators
ti_marketfiand pandas-ta-classicmarketficompute the same form, but divide unconditionally: both emit ±Inf on a zero-volume bar where this returns 0. - The four-state green/fade/fake/squat colour code charting packages overlay is derived from the signs of the bar-to-bar change in this index and in volume. It is an interpretive layer, not part of the series;
outRealis the scalar only.